

 67 Monroe Avenue, Pittsford, NY 14534 / 9am - 4pm M-F


By Joseph Zappia, Co-Chief Investment Officer
The 5-year Treasury closed at 5.03% on September 24, its highest level since 20071. The 10-year closed at 5.18%2. Headlines are treating this as bad news for bonds. We see it differently.
1. This Is Not a Rate Call
We are not predicting where interest rates go next. Nobody can do that reliably, and we don’t try.
What we can do is the math. A bond pays you interest every year. If rates rise, the bond’s price dips. If rates fall, its price climbs. The interest you collect is your cushion. When interest rates are high, the cushion is thick. When rates are near zero, there is almost no cushion at all.
That math is what has changed. Not our view of the Fed.
2. The Asymmetry
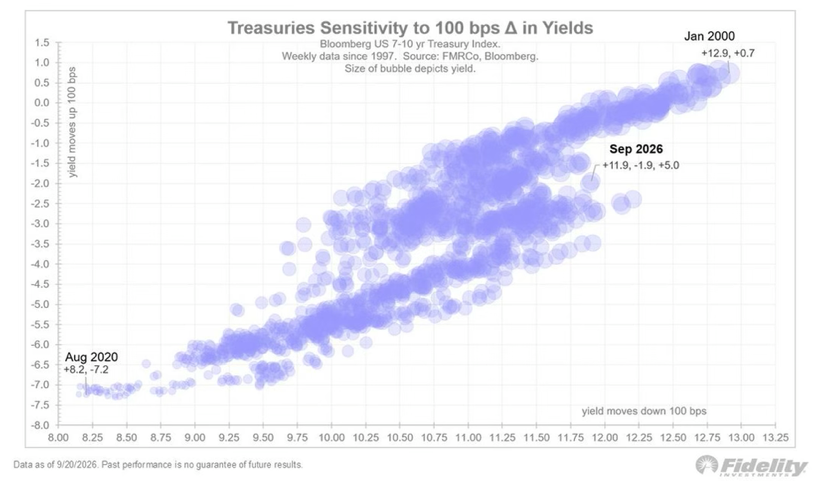
Source: FMRCo, Bloomberg, via Weight of Evidence. Bloomberg US 7–10 Yr Treasury Index, weekly data since 1997, as of 9/20/2026. Past performance is no guarantee of future results.
3. Then and Now
| When you bought | If rates fall 1% | If rates rise 1% | What it means |
|---|---|---|---|
| Intermediate-term Treasury bonds (Bloomberg US 7–10 Yr Treasury Index, from the Fidelity chart) | |||
| August 2020
|
+8.2% | −7.2% | Risked about $1 to make $1 |
| September 24, 2026 (today) | +11.9% | −1.9% | Risk about $1 to make $6 |
| January 2000
|
+12.9% | +0.7% | Came out ahead either way |
| 5-year Treasury note bought at 5.03%, one year later (LVW calculation) | |||
| September 24, 2026 (today) | +8.7% | +1.6% | Comes out ahead either way |
Fidelity figures are read from the chart labels. 5-year row: 5.03% semiannual coupon bought at par, rate move held for one year, flat yield curve. Hypothetical interest rate scenarios; not actual client results.
Today the potential gain is about six times the potential loss. When the odds lean this way, patient bond investors have historically been rewarded.
4. What This Means for How We Invest
For several years, LVW has maintained its bond portfolios at a shorter duration than the broad bond market. In industry terms, our portfolios have generally been positioned below the duration of the Bloomberg U.S. Aggregate Bond Index, meaning they have had less sensitivity to changes in interest rates than the broader index.
The reason was the math in the table above, and that math has now flipped. Real yields, meaning what bonds pay after inflation, are among the highest in years. The 10-year inflation-protected Treasury (TIPS) auctioned on September 17 at a 2.653% real yield, the highest for that maturity since October 20083.
The question we have always asked is: at what point does it make sense to own a normal amount of duration? Our answer is simple. When yields are high enough to offset the risk of rates going higher. Today, for the first time in years, that test is close to being met.
5. A Word on Municipal Bonds
Treasuries sold off first. Last week the selling moved into municipal bonds, while corporate bonds were largely spared. Adjusted for interest-rate sensitivity, munis have lagged broad taxable bond funds for several weeks.
For investors in the maximum federal tax bracket (37% plus the 3.8% net investment income tax), that matters. Interest on most municipal bonds is free of federal income tax, so a hypothetical 5% tax-free yield is worth about 8.4% in taxable terms. The same cushion that protects Treasury investors applies here, and it is thicker after tax. Unlike Treasuries, munis carry credit and trading risk, so issuer quality matters
6. The Other Side
Rates can keep rising. The Fed raised rates this month for the first time since 2023, and Bloomberg reports markets expect four more increases over the next year. Inflation has been above the Fed’s 2% target for five and a half years. A 5% yield is a cushion, not a floor.
We aren’t calling the top in rates.
Investors are finally being paid to own bonds.
Sources:
1 Bloomberg, September 24, 2026
2 Federal Reserve H. 15, September 24, 2026
3 TIPSWatch, September 24, 2026
Disclosure: This information is provided by LVW Advisors for general information and educational purposes based upon publicly available information from sources believed to be reliable. LVW Advisors cannot assure the accuracy or completeness of these materials. Results are based on a limited number of historical periods and may not reflect future market conditions. Past performance is not indicative of future results. Returns shown exclude dividends, transaction costs, fees, and taxes, which would impact actual results.
This analysis does not represent the performance of any specific portfolio or strategy and should not be construed as investment advice or a recommendation to buy or sell any security. Investors should review applicable offering documents and consider their individual circumstances before making investment decisions. All investments involve risk, including the possible loss of principal. LVW Advisors is a registered investment adviser.